Dos and Don’ts of Driving With Broad Form Coverage
Broad form coverage works differently from a standard auto policy, so it’s important to know exactly who and what your policy covers. Learning the dos and don’ts of driving with broad form coverage helps you use the policy within its limits instead of expecting protection it doesn’t provide. Once you understand that difference, you can make better decisions each time you get behind the wheel.
Know Who Has Coverage
Broad form coverage centers on the person named on the policy. If that person drives an eligible personal-use vehicle, the policy may provide liability protection according to its terms and limits. However, coverage doesn’t automatically transfer to another person just because that person drives a vehicle you own. You need to treat that distinction seriously.
That structure makes broad form coverage useful in certain situations, but it also creates a clear boundary. You shouldn’t assume a spouse, friend, roommate, or family member receives protection through your policy. Instead, anyone else who drives should have appropriate coverage of their own.
Understand Liability Protection
Liability coverage helps address injuries or property damage for which you become legally responsible after an accident, subject to policy terms and limits. In Washington, drivers generally must carry at least $25,000 of bodily injury liability for one person, $50,000 per accident, and $10,000 for property damage. Your policy declarations show the limits you purchased.
When driving with broad form coverage, review the policy limits carefully so you understand how much liability protection you have. An accident may cost more than the amount your insurer agrees to pay. Higher limits may be available, depending on the insurer and policy.
Check Your Vehicle Use
Broad form policies may restrict the types of vehicles or driving activities they cover. Personal-use passenger vehicles commonly fit the policy structure, while business driving or certain vehicle types may fall outside it. Your actual contract determines what applies.
Keep these habits in mind whenever your driving situation changes:
- Do review your policy before driving an unfamiliar vehicle
- Do confirm that the vehicle fits your policy’s definitions
- Don’t assume work-related driving receives personal coverage
- Don’t treat every motor vehicle as eligible
- Do ask your agent when your situation falls outside your normal routine
Don’t Expect Vehicle Repairs
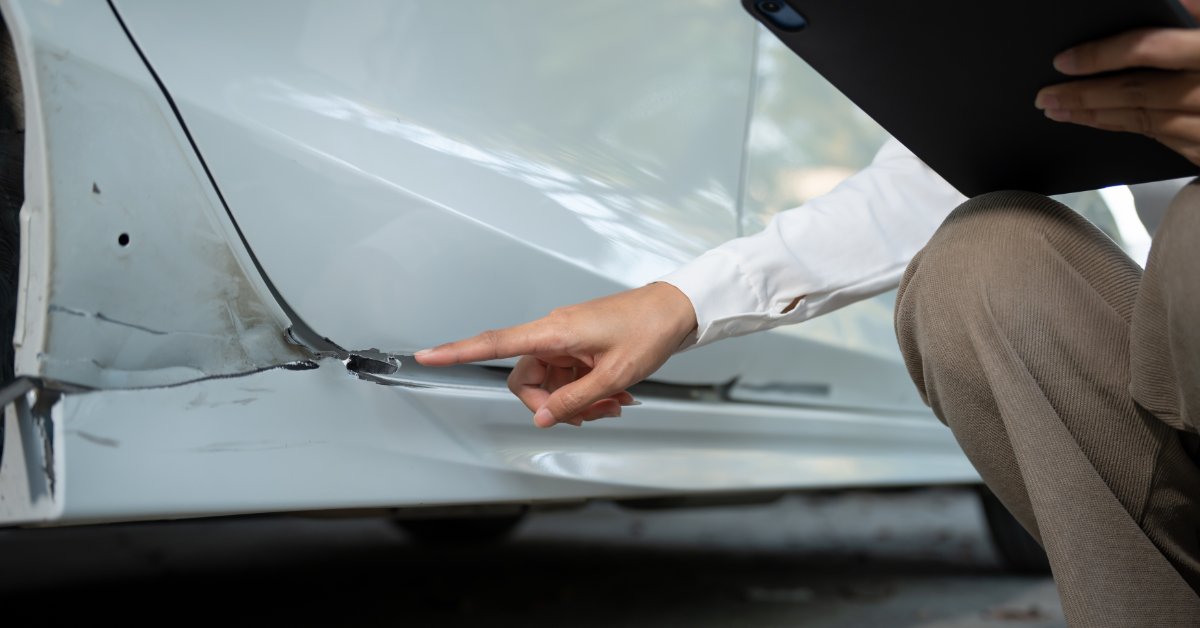
Broad form coverage generally doesn’t provide collision or comprehensive protection for physical damage to the vehicle you’re driving. If you cause a crash, liability coverage may address covered damage you cause to another person’s property, but repairs to the car you were driving are a separate issue. That gap deserves attention if you own a valuable vehicle.
You should also consider this limitation if your vehicle has a loan or lease. Lenders commonly require physical damage coverage to protect their financial interest in the vehicle. Broad form coverage may therefore conflict with financing requirements when it doesn’t include the required protection.
Compare Price With Protection
If you’re looking for cheap broad form insurance, price is only part of the decision. A lower premium may work for your budget, but you still need to check whether the policy limits and restrictions fit the way you drive. Broad form coverage can be useful when its driver-specific structure matches your situation, so it’s worth comparing the protection you get with the amount you pay.
Broad form coverage may cost less than other arrangements because the insurer accepts a narrower set of risks. Therefore, compare policies based on what they cover rather than focusing solely on the monthly payment. A policy that misses a certain protection you need may create a much larger expense later.
Review Optional Coverage
Liability isn’t necessarily the only protection available with a broad form policy. Depending on your state and insurer, you may have access to optional coverage that addresses other risks. Washington insurers, for example, must offer certain protections such as personal injury protection, although policyholders may reject PIP in writing.
As you compare your coverage options, take a closer look at the protection available to you by:
- Asking about uninsured or underinsured motorist coverage
- Reviewing available personal injury protection
- Checking the limits offered with each option
- Reading any written rejection forms carefully
- Keeping copies of your current policy documents
Keep Your SR-22 Current
Some drivers purchase broad form coverage while they have an SR-22 filing requirement. An SR-22 isn’t insurance itself; it’s proof filed with the state showing that you carry qualifying liability coverage. If your policy qualifies and your insurer offers filings, broad form coverage may support that requirement.
You shouldn’t assume every broad form policy automatically includes an SR-22 filing. Tell your agent when you have a filing requirement and confirm that the insurer will submit it to the correct state. Additionally, avoid canceling or changing coverage without checking what the change means for your filing status.
Recheck Changing Circumstances
Broad form coverage may suit you today, but it may not be the right fit forever. Buying a financed vehicle may change the type of protection you need because your lender may require comprehensive and collision coverage. Another driver beginning to use your vehicle regularly may also create a coverage issue.
Revisit your policy when your driving habits change rather than waiting until renewal without thinking about it. Explain the new situation to your agent and ask which parts of your current coverage still apply. You’ll get a clearer picture of any adjustments you may need.
Read Your Actual Policy
General explanations give you a useful starting point, but your policy controls the coverage you purchased. Definitions, exclusions, limits, and endorsements may change what applies in a particular accident. Therefore, review your declarations page along with the policy language instead of relying on the name “broad form.”
Ask questions whenever wording seems unclear. You deserve to know what protection you have before a claim puts the policy to the test. That knowledge lets you drive with realistic expectations rather than assumptions.
Broad form coverage can be practical when its driver-specific structure matches the way you use vehicles, but it requires you to be aware of its boundaries. Serenity Group helps drivers sort through specialized coverage questions to better understand options connected with SR-22 requirements. Reach out if you want help reviewing what may fit your circumstances.
Recent Comments