Selling your car may seem like a natural reason to cancel your insurance, especially when you don’t expect to replace the vehicle right away. However, canceling your coverage creates a gap in your insurance history that may become relevant when you shop for another policy. If you’re wondering how to keep insurance history without a car, you may have options that don’t require insuring a vehicle you no longer own. The right approach depends on your driving plans and any active financial responsibility requirements.

Why Insurance History Matters

Insurers may review your prior coverage when you apply for a new policy. A period without insurance doesn’t automatically mean you’ve done something wrong, particularly if you didn’t own a vehicle. Still, maintaining coverage gives you a record of continuous insurance to show when you return to regular driving.

Your driving situation also deserves attention during a car-free period. You might occasionally borrow someone else’s vehicle or use a rental car. If you expect to drive regularly, appropriate insurance can protect you while you’re behind the wheel while also maintaining your coverage history.

After You Sell Your Car

Once you no longer own your vehicle, your existing policy may no longer fit your situation. Instead of canceling it right away, ask your insurer what coverage fits your driving plans. You’ll also want to check for any state filing requirements that remain active.

Consider these questions as you decide what comes next:

  • Do you expect to borrow vehicles regularly?
  • Will you rent cars during this period?
  • Do you still have an active SR-22 requirement?
  • Does another household member regularly give you access to a car?
  • When do you expect to purchase another vehicle?

Consider Non-Owner Coverage
A man in business clothing standing with question marks and arrows drawn around him on a white background.

A non-owner policy may be appropriate when you drive but don’t own a vehicle. It generally provides liability coverage for you as a driver rather than for damage to the vehicle you’re driving. Coverage details vary, so review the policy terms rather than assuming it works like a standard vehicle policy.

If your goal is to keep insurance history while living without a car, maintaining a non-owner policy may help you avoid an interruption in coverage. Eligibility depends on your circumstances, so give the insurer an accurate picture of your driving situation. Additionally, the insurer will need accurate information about your driving circumstances.

Borrowed Cars Need Context

Borrowing a vehicle can affect your coverage differently depending on the situation. The vehicle owner’s policy may provide primary coverage, while your policy may apply according to its own terms and limits. Regular access to one vehicle can also affect your eligibility for non-owner coverage. Therefore, explain your borrowing arrangement to the insurer rather than assuming your policy covers every situation the same way.

When SR-22 Requirements Remain

Selling your car can change the type of coverage you need, but it may not change an existing requirement. If a state or court still requires an SR-22 filing, you’ll need to keep that proof of financial responsibility active. An SR-22 isn’t a separate insurance policy; instead, it’s a filing that shows you carry the coverage required in your situation.

If you no longer own a vehicle, non-owner SR22 insurance may be an option worth discussing with an insurer. This arrangement generally combines non-owner auto coverage with the required filing, allowing you to maintain the required proof while you don’t own a car. Because filing rules and coverage requirements vary by state, confirm what applies to you before making changes to your policy.

Avoid an SR-22 Lapse

If you need to change policies while an SR-22 requirement remains active, pay close attention to the timing. Ask your insurer when your current coverage ends and when the replacement policy takes effect so you can avoid a gap. Also confirm that the new insurer can complete the required filing before you cancel your existing policy.

After you switch policies, keep documentation showing the effective dates of your new coverage. This gives you a clear record of the transition if questions come up later and helps you switch coverage without accidentally interrupting an active filing requirement.

Household Vehicle Access

Living with someone who owns a car can change your insurance options. If you regularly drive that vehicle, a non-owner policy may not fit because insurers may treat regular household access differently from occasional borrowing. Discuss that access clearly when you request coverage.

You should also avoid assuming another person’s policy automatically covers every driver in the home. Policy terms vary, as do requirements concerning household drivers. Give your insurer an accurate picture of who drives the vehicle and how regularly you use it.

Keep Coverage Records Handy
A close-up of a person filling out a car insurance form beside a calculator, pen, and small vehicle model on a desk.

Keeping your policy records organized can make your insurance history easier to document later. Save documentation whenever you change coverage, especially during a period when you don’t own a vehicle. You can also refer to these records when completing future insurance applications.

Keep copies of information such as:

  • Policy declarations showing your coverage dates
  • Cancellation notices from previous policies
  • Non-owner policy documents you receive
  • SR-22 filing confirmations when applicable
  • Renewal documents showing continued coverage

When You Rarely Drive

You may decide that you won’t drive at all after selling your vehicle. In that situation, paying for a non-owner policy solely to maintain insurance history may not make sense for everyone. If you return to driving later, an insurer can evaluate your coverage needs at that point.

An active SR-22 requirement changes that decision because you may still need qualifying coverage despite not owning a car. Your licensing requirements may also remain in effect after you sell your vehicle. Check those obligations before allowing coverage to end.

Buying Another Car Later

When you’re ready to buy another vehicle, contact an insurer before you begin driving it. A non-owner policy generally doesn’t provide the same protection as a policy written for a vehicle you own. You’ll need coverage that reflects your new ownership situation.

Maintaining coverage during your car-free period also gives you a clearer insurance record when you shop for a new policy. Still, continuous coverage is only one factor an insurer may consider when setting your new premium. Continuous coverage is only one part of that review.

Going without a car doesn’t necessarily mean letting your insurance coverage lapse. Depending on your driving habits and filing requirements, a non-owner policy may help you maintain coverage while you’re between vehicles.

If an SR-22 remains part of your situation, Serenity Group can help you review coverage that fits a driver who doesn’t currently own a car. Contact Serenity Group to discuss your circumstances and find out what options may help you maintain the coverage you need.
Broad form coverage works differently from a standard auto policy, so it’s important to know exactly who and what your policy covers. Learning the dos and don’ts of driving with broad form coverage helps you use the policy within its limits instead of expecting protection it doesn’t provide. Once you understand that difference, you can make better decisions each time you get behind the wheel.

Know Who Has Coverage

Broad form coverage centers on the person named on the policy. If that person drives an eligible personal-use vehicle, the policy may provide liability protection according to its terms and limits. However, coverage doesn’t automatically transfer to another person just because that person drives a vehicle you own. You need to treat that distinction seriously.

That structure makes broad form coverage useful in certain situations, but it also creates a clear boundary. You shouldn’t assume a spouse, friend, roommate, or family member receives protection through your policy. Instead, anyone else who drives should have appropriate coverage of their own.

Understand Liability Protection

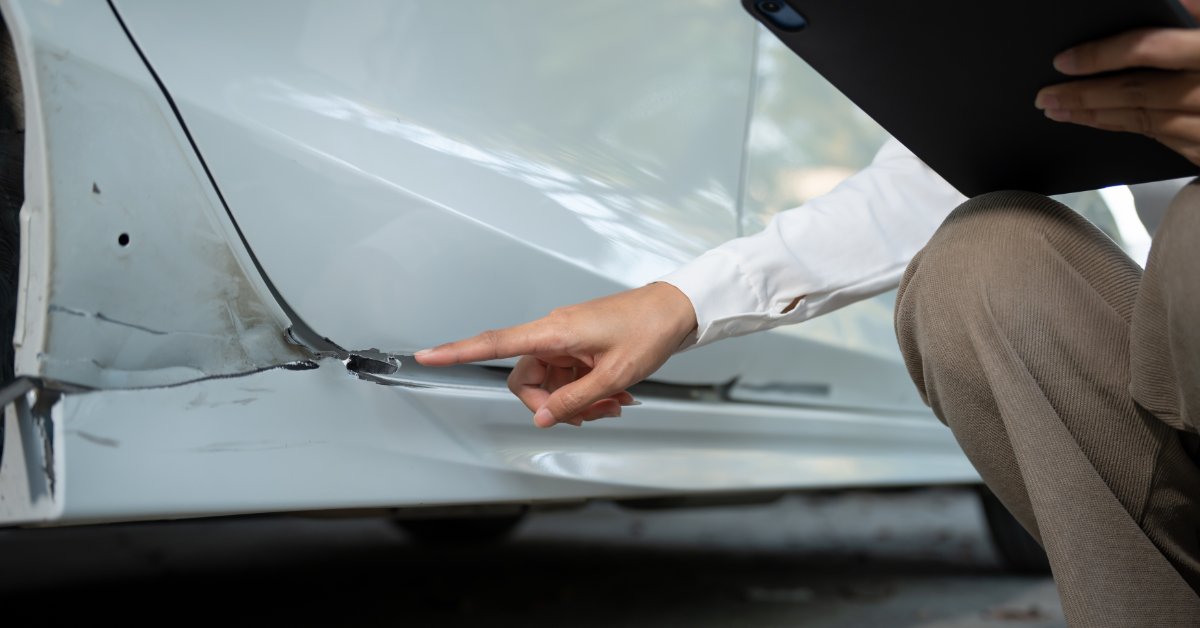
A close-up of a person pointing to scratches and dents on a white car door while holding a black clipboard.

Liability coverage helps address injuries or property damage for which you become legally responsible after an accident, subject to policy terms and limits. In Washington, drivers generally must carry at least $25,000 of bodily injury liability for one person, $50,000 per accident, and $10,000 for property damage. Your policy declarations show the limits you purchased.

When driving with broad form coverage, review the policy limits carefully so you understand how much liability protection you have. An accident may cost more than the amount your insurer agrees to pay. Higher limits may be available, depending on the insurer and policy.

Check Your Vehicle Use

Broad form policies may restrict the types of vehicles or driving activities they cover. Personal-use passenger vehicles commonly fit the policy structure, while business driving or certain vehicle types may fall outside it. Your actual contract determines what applies.

Keep these habits in mind whenever your driving situation changes:

  • Do review your policy before driving an unfamiliar vehicle
  • Do confirm that the vehicle fits your policy’s definitions
  • Don’t assume work-related driving receives personal coverage
  • Don’t treat every motor vehicle as eligible
  • Do ask your agent when your situation falls outside your normal routine

Don’t Expect Vehicle Repairs

Broad form coverage generally doesn’t provide collision or comprehensive protection for physical damage to the vehicle you’re driving. If you cause a crash, liability coverage may address covered damage you cause to another person’s property, but repairs to the car you were driving are a separate issue. That gap deserves attention if you own a valuable vehicle.

You should also consider this limitation if your vehicle has a loan or lease. Lenders commonly require physical damage coverage to protect their financial interest in the vehicle. Broad form coverage may therefore conflict with financing requirements when it doesn’t include the required protection.

Compare Price With Protection

If you’re looking for cheap broad form insurance, price is only part of the decision. A lower premium may work for your budget, but you still need to check whether the policy limits and restrictions fit the way you drive. Broad form coverage can be useful when its driver-specific structure matches your situation, so it’s worth comparing the protection you get with the amount you pay.

Broad form coverage may cost less than other arrangements because the insurer accepts a narrower set of risks. Therefore, compare policies based on what they cover rather than focusing solely on the monthly payment. A policy that misses a certain protection you need may create a much larger expense later.

Review Optional Coverage

Liability isn’t necessarily the only protection available with a broad form policy. Depending on your state and insurer, you may have access to optional coverage that addresses other risks. Washington insurers, for example, must offer certain protections such as personal injury protection, although policyholders may reject PIP in writing.

As you compare your coverage options, take a closer look at the protection available to you by:

  • Asking about uninsured or underinsured motorist coverage
  • Reviewing available personal injury protection
  • Checking the limits offered with each option
  • Reading any written rejection forms carefully
  • Keeping copies of your current policy documents

Keep Your SR-22 Current

A close-up of a person in a suit holding a small, yellow umbrella over a red toy car on a white table.

Some drivers purchase broad form coverage while they have an SR-22 filing requirement. An SR-22 isn’t insurance itself; it’s proof filed with the state showing that you carry qualifying liability coverage. If your policy qualifies and your insurer offers filings, broad form coverage may support that requirement.

You shouldn’t assume every broad form policy automatically includes an SR-22 filing. Tell your agent when you have a filing requirement and confirm that the insurer will submit it to the correct state. Additionally, avoid canceling or changing coverage without checking what the change means for your filing status.

Recheck Changing Circumstances

Broad form coverage may suit you today, but it may not be the right fit forever. Buying a financed vehicle may change the type of protection you need because your lender may require comprehensive and collision coverage. Another driver beginning to use your vehicle regularly may also create a coverage issue.

Revisit your policy when your driving habits change rather than waiting until renewal without thinking about it. Explain the new situation to your agent and ask which parts of your current coverage still apply. You’ll get a clearer picture of any adjustments you may need.

Read Your Actual Policy

General explanations give you a useful starting point, but your policy controls the coverage you purchased. Definitions, exclusions, limits, and endorsements may change what applies in a particular accident. Therefore, review your declarations page along with the policy language instead of relying on the name “broad form.”

Ask questions whenever wording seems unclear. You deserve to know what protection you have before a claim puts the policy to the test. That knowledge lets you drive with realistic expectations rather than assumptions.

Broad form coverage can be practical when its driver-specific structure matches the way you use vehicles, but it requires you to be aware of its boundaries. Serenity Group helps drivers sort through specialized coverage questions to better understand options connected with SR-22 requirements. Reach out if you want help reviewing what may fit your circumstances.

A coverage gap can happen faster than you expect when you miss a payment, or you change policies without coordinating the dates. If you have an SR-22 filing, a lapse could create another problem because your insurer may have to notify the state when required coverage ends. The 8 best ways to avoid a gap in auto insurance coverage come down to keeping your policy active while handling changes with care. A little attention now can save you from scrambling to restore coverage later.

Know What Counts as a Gap

A gap in coverage is a period when you don’t have an active auto insurance policy that meets your needs or state requirements. The gap might last a day or much longer, but you shouldn’t assume that a short lapse has no consequences. If you’re obligated to maintain an SR-22, continuous coverage deserves extra attention because the filing shows your state that you carry the required financial responsibility coverage.

You may also run into trouble if you cancel one policy before another is active. Therefore, check the effective date whenever you replace coverage. You want the new policy ready to take over as the old one ends, without an uncovered period between them.

Keep Payments on Schedule

A close-up of a person holding a blue credit card while touching a laptop keyboard, with a phone and notebook nearby.

Missing a premium payment may put your policy at risk of cancellation, depending on your policy terms and applicable state rules. Don’t assume you’ll always have extra time after the due date. Instead, review your billing schedule and pay by the stated deadline so that an avoidable oversight doesn’t interrupt your coverage.

Automatic payments can make this easier, but they still need occasional attention. An expired card or changed bank account may cause a scheduled transaction to fail. Additionally, check payment confirmations so you know your insurer has received the money.

Update Your Payment Information

If you replace a debit or credit card, update the payment method attached to your policy promptly. The same applies when you close an account used for automatic withdrawals. Check the next payment date after making the change so you know your new information is in place. This small habit gives you time to address billing problems before they threaten your coverage.

Keep Contact Details Current

Your insurer needs accurate contact information to reach you about billing or policy changes. Update your address when you move, and make sure your preferred email still works. If your phone number changes, updating it can make time-sensitive communication easier. Staying reachable also reduces the chance that you’ll overlook a notice requiring your attention.

Respond to Policy Notices

Insurance notices may contain deadlines that affect whether your policy stays active. Read messages from your insurer when they arrive, particularly if they address cancellation or nonrenewal. Avoiding unexpected gaps in auto insurance work best when you respond while your current policy remains active.

When a policy notice arrives, a few key steps include:

  • Confirming the date the notice takes effect
  • Identifying any payment amount that’s due
  • Checking whether the insurer requests information
  • Contacting the insurer if instructions aren’t clear
  • Saving confirmation after resolving the issue

Coordinate Every Policy Change

Switching insurers calls for more than finding a lower quote. Keep your existing policy active until you’ve confirmed that the replacement policy has started. If you have an SR-22 filing, check that your new insurer can submit it and that they understand the obligations related to your driving record.

When you’re comparing policies, you might look for cheap auto insurance for high-risk drivers while trying to keep your SR-22 in place. Price is important, but you also want to confirm that the new insurer can handle your required filing before you make the switch. Once you’ve confirmed the new policy’s effective date and filing details, you can coordinate the change without accidentally leaving a gap between policies.

Handle Vehicle Changes Carefully

Selling your car doesn’t necessarily mean you no longer need insurance, particularly when an SR-22 requirement remains active. If you won’t own a vehicle for a while, ask whether a non-owner policy fits your situation instead of simply canceling your current policy. Your state obligations will help determine what coverage you need. Clarifying that point can help you maintain required financial responsibility while your vehicle ownership changes.

Consider Changes in Driving Habits

A close-up of a person holding a steering wheel inside a car, with sunlight shining across the dashboard and windshield.

You may have periods when you expect to drive very little, such as while working from home or leaving a vehicle parked for an extended time. Don’t cancel coverage simply because the car won’t be on the road regularly. Your policy obligations and any active SR-22 can continue regardless of how frequently you drive.

Instead, contact your insurer when your driving habits change and ask what options apply to your situation. If you have an SR-22, confirm that any policy adjustment will keep the required filing active. That conversation can help you make an informed change without accidentally creating a lapse.

Pay Attention at Renewal

Renewal time gives you a useful checkpoint for confirming that your coverage will continue without interruption. Read the renewal documents and note the next policy period. If your insurer won’t renew the policy, use the advance notice to arrange replacement coverage. You can also confirm that an ongoing SR-22 remains connected to the appropriate policy.

Protect Your SR-22 Status

An SR-22 isn’t a separate insurance policy; it’s a certificate your insurer files to show that you carry financial responsibility coverage required by your state. If the policy tied to your SR-22 ends, your insurer may report the lapse to the state, which could affect your license status or how long the filing stays in place. Since they can vary by state, check the rules that apply to your license rather than relying on another driver’s experience.

When your policy or driving situation changes, consider asking the following:

  • When does my current policy expire?
  • When will replacement coverage begin?
  • Will my SR-22 filing remain active?
  • Does this change affect my filing period?
  • What confirmation will I receive afterward?

Keeping records adds another layer of protection against confusion. Save policy documents that show when coverage begins and ends, along with confirmations for payments or requested changes. You don’t need a complicated filing system; a secure digital folder can keep current documents easy to find.

Staying continuously insured takes attention, but it shouldn’t be a constant source of stress. When you watch important dates and respond promptly to policy changes, you’re less likely to discover a lapse after it has already caused a problem.

Serenity Group helps drivers navigate SR-22 coverage requirements, so reach out if you need help reviewing your options and keeping your filing on track. Take a few minutes today to check your next payment and policy expiration date, then address anything that could interrupt your coverage.

A state filing requirement can create questions that reach beyond the person who received the violation, especially when a shared vehicle or loan connects two people. If you’re trying to understand how SR22 insurance affects co-signers or spouses, the biggest point is that one person’s filing requirement doesn’t automatically become another person’s state filing obligation. Still, a shared household or vehicle can change what an insurer needs to know about the people connected to the policy. Once you separate the filing requirement from the loan and policy relationships, the situation itself becomes much easier to sort out.

(more…)

You may not own a car, but your driving record can still create insurance requirements that follow you whenever you get behind the wheel. After certain violations or license actions, a state may require proof that you carry the required liability coverage before restoring or maintaining your driving privileges. That’s where non-owner policies and additional state filings may need to work together, depending on the requirement your state places on your record. Knowing what the filing does can help you avoid treating a non-owner policy as a complete solution when the state expects something more.

(more…)

When Virginia requires you to carry an FR44 filing, keeping your driving privileges in good standing depends on staying ahead of the requirement. Your insurer handles the filing, but you still need to keep the qualifying policy active and make choices that don’t create an unexpected break in coverage. This ultimate guide explains what you need to know to maintain FR44 compliance in Virginia. With a few practical habits, you can keep track of your responsibility and know when it’s worth asking questions.

(more…)

Tagged with:

Shopping for FR44 coverage can put you in unfamiliar territory, especially when the price you receive doesn’t match what you expected. In Florida, an FR44 verifies that you carry the higher liability coverage required after certain DUI convictions, but that filing requirement isn’t the only information an insurer considers when calculating your premium. Knowing how insurance claims history affects FR44 rates in Florida gives you useful context when you compare quotes that meet the state’s requirements.

(more…)

Growing a business often means expanding your fleet to meet rising customer demand and improve daily operations. Every new vehicle creates opportunities for greater efficiency, but it also introduces new responsibilities that require careful planning. Understanding how fleet insurance works before adding vehicles helps you avoid delays, unexpected costs, and coverage gaps. When you know what to expect, you can make confident decisions that protect your company and your drivers.

Commercial fleets rarely stay the same for long because businesses evolve with changing workloads and customer needs. Whether you purchase one additional truck or several service vans, every change affects your insurance policy. Insurance providers evaluate several factors before they approve coverage, and these details influence your premiums and policy terms. Here’s a look at what to expect when adding vehicles to a fleet policy.

(more…)

Maintaining an SR22 filing requires more than simply purchasing an auto insurance policy. Drivers must keep continuous coverage because the insurance company reports cancellations or lapses directly to the state. When coverage ends unexpectedly, drivers often face license suspensions, reinstatement fees, and additional financial challenges that could have been avoided with proactive policy management.

High-risk drivers can avoid interruptions and remain compliant with state requirements when they understand why insurers cancel SR22 policies. Many policy cancellations result from preventable issues rather than unexpected decisions by the insurance company. By recognizing the most common causes, drivers can protect their driving privileges and maintain the coverage they need throughout the required filing period. Serenity Group discusses why insurers cancel SR22 policies without notice and what you can do if this happens to you.

(more…)

A serious driving violation like a driving-under-the-influence (DUI) conviction can create financial responsibility requirements that drivers must satisfy before regaining driving privileges. Two possible methods include an SR22 filing attached to an auto policy and a license bond backed by a surety company.

(more…)

Top